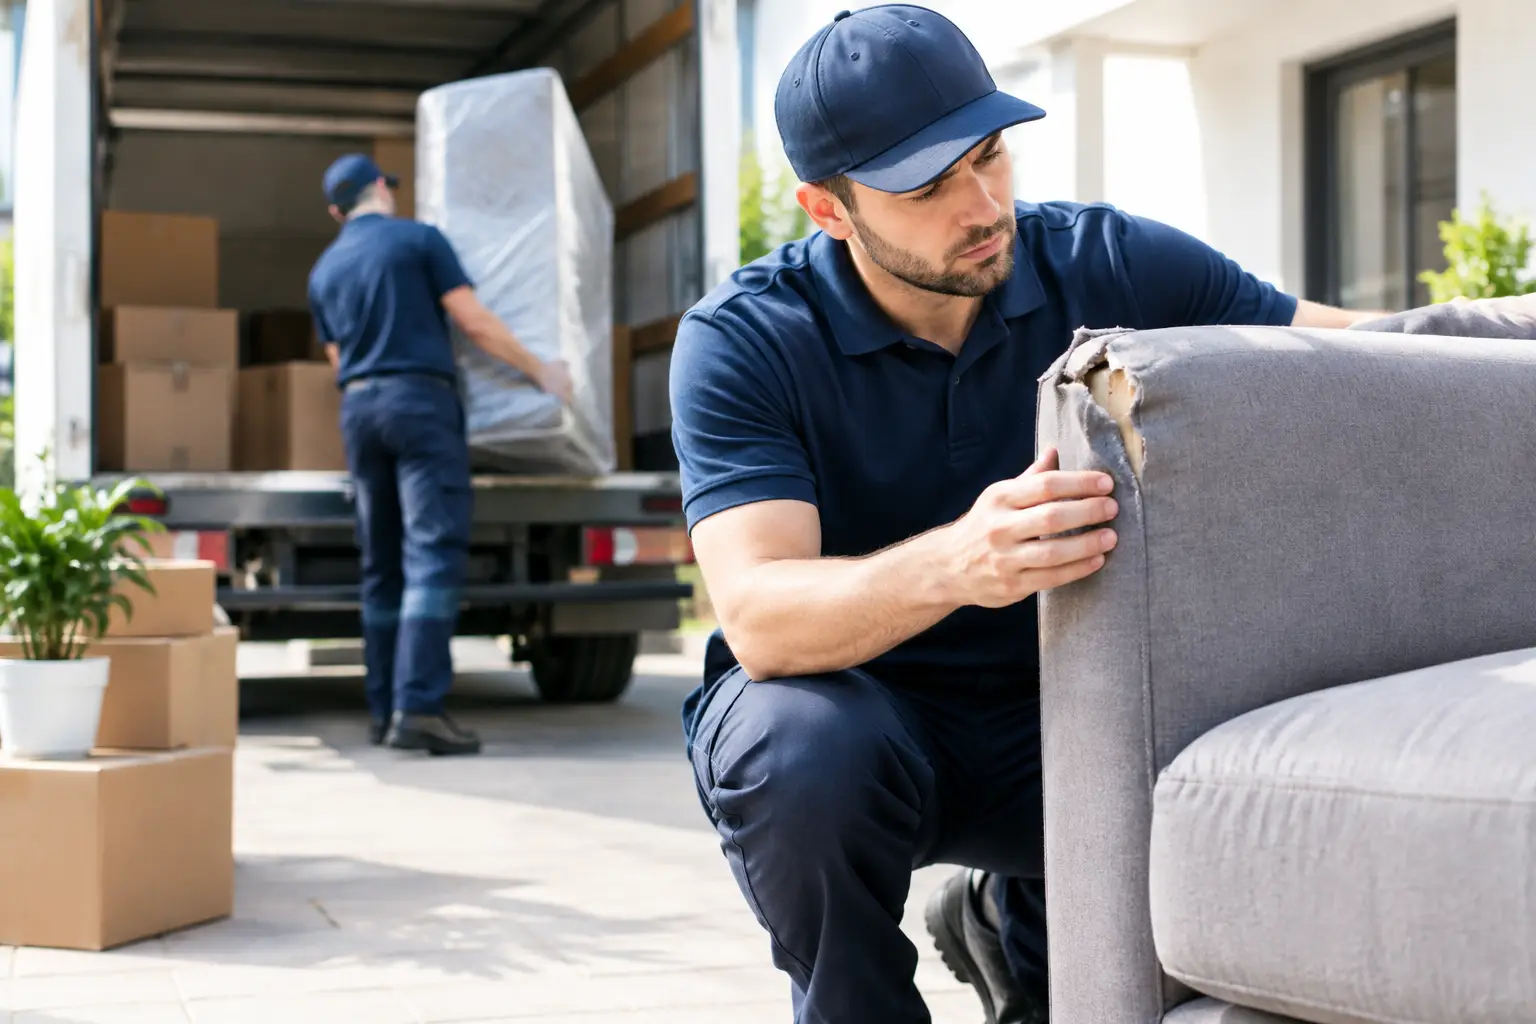
A scratch in the parquet, a damaged chest of drawers or a box of broken crockery: damage during a move is annoying, but no reason to panic. What matters is that you react correctly when it comes to a moving company's liability for damage. Anyone who documents damage, keeps to the deadlines and checks the contract carefully lays a good foundation for a quick resolution.
When is a moving company liable for damage?
If you hire a professional moving company, it takes responsibility for your belongings from the moment it takes them over until they are delivered. If a piece of furniture is damaged during this time, a box is lost or something does not arrive at the destination, the company is in principle liable under the rules of the German Commercial Code (Handelsgesetzbuch).
That does not apply automatically to every case of damage, however. The moving company does not have to pay if it can prove that the damage would have been unavoidable even with the greatest care. Liability can also be limited if you packed yourself, dismantled or assembled furniture yourself, or carried heavy items together with helpers.
In practice it therefore comes down to a simple question: who had the item in their hands, and who was responsible for that step of the work? If your wardrobe was damaged by the hired movers while being carried, the starting position is usually clearer than with a box packed by the customer with inadequate protection.
Understanding the statutory liability limit
For a private move, the moving company's statutory liability is generally limited. It stands at 620 euros per cubic metre of load space needed for your move. That sounds abstract at first, but it is important: compensation is not automatically based on the new price of each individual item.
For a move of 25 cubic metres, for example, the statutory maximum liability comes to 15,500 euros. Whether that sum is enough for your household depends on its value. Anyone having high-quality designer furniture, art, musical instruments or expensive technical equipment transported should check the cover especially carefully beforehand.
The statutory limit is not a licence for poor work. It merely determines up to what amount a company ordinarily has to answer for damage it must compensate. Where there is intent, or recklessness with awareness that damage would probably result, other standards can apply. Such cases are hard to prove, however, and for larger losses should be examined by a specialist.
New value, current value and repair costs
Even when liability applies, you do not always get back the purchase price you once paid. For used furniture and older electrical appliances, the current value is often taken into account. If a repair makes sense and is cheaper than a replacement, the company can cover the necessary repair costs.
So do not photograph the item only in its damaged state. Receipts, earlier photos, model names and cost estimates help to document its age, condition and value clearly. For a valuable one-off piece, an expert report can make sense before you agree to a lump-sum settlement.
Kinds of damage that can matter in a move
Many people think of liability only in terms of broken items. In fact, different kinds of damage can play a part. These include damage to the belongings being moved as well as damage to the flat, the stairwell or the lift.
If a washing machine is damaged in transit, for instance, that concerns the goods being moved. If a deep scratch is made in the floor of your old or new flat during carrying, that is property damage to the building or its fittings. For tenants in particular this can be important, because the landlord may object to the damage when the flat is handed over.
Report smaller damage straight away as well. A superficial scratch can later turn out to be deeper damage to paintwork or wood. If you are unsure, document it first and ask the company for a written statement.
Reporting damage correctly: the deadlines that count
There is a lot going on on moving day. Even so, a short walk-round is worth it before you finally sign off the work. Check furniture, boxes, doors, floors and the stairwell, together with the crew if possible. Have visible damage noted immediately on the delivery note or moving report.
If you only discover damage while unpacking, you need to act promptly. Damage that was not immediately apparent should be reported to the moving company in text form within 14 days of delivery. An email is practical for this, because the time of sending remains traceable. Describe the damage specifically, add photos and give your order or invoice number.
Missing this deadline does not necessarily mean losing every claim. However, it is then often presumed that the goods were delivered undamaged. That makes proof considerably harder. So do not wait to see whether a problem perhaps resolves itself.
Claims arising from a moving contract are generally subject to a limitation period of one year. Longer periods can apply in cases of intent or recklessness. You should not rely on that for the initial damage report, though: the earlier the company receives all the information, the better the matter can be examined.
How to document the damage convincingly
A good damage report does not have to be complicated. Clear facts matter more than long speculation. Record when and where the damage was discovered, which item is affected and what it looked like before. Take photos from several angles and keep damaged parts, packaging or fragments until the settlement is resolved.
If possible, ask someone who was present during the move for a short confirmation. For damage to the building, photos taken directly after the incident and a note to the landlord or property management can also help. Do not have repairs carried out hastily if that could destroy the evidence. For urgent measures, such as a damaged water connection, document everything as fully as possible beforehand.
When additional transport insurance makes sense
Statutory liability is adequate for many ordinary private moves. But it is not enough in every situation. Additional transport insurance can make sense if the total value of your household exceeds the liability limit or particularly valuable individual pieces are being transported.
Before taking it out, check exactly what is insured. Some policies cover only damage during transport, others include packing, loading and unloading or interim storage. Also ask whether an excess applies and whether you have to declare valuables individually.
Cash, important documents, jewellery, keys and irreplaceable personal papers do not belong in the removal van as a matter of principle. Transport these things yourself. That not only reduces the risk but also avoids arguments about whether an item was part of the goods to be moved at all.
Check the contract and quote before booking
The best claims settlement is the one you never need. When looking at quotes, pay attention not only to the final price but also to the agreed scope of services. Does it state clearly whether packing materials, packing service, furniture assembly, a no-parking zone and insurance are included?
Clarify particular risks in advance too. A piano, a large fridge, narrow stairwells or the absence of a lift change the effort and the risk. If a company only learns of these on moving day, delays, extra costs and misunderstandings can follow.
With several quotes, a direct comparison of services and terms is worthwhile. Through Umzigo you can request suitable quotes from vetted moving companies free of charge and without obligation, set prices against each other and ask specifically about liability and additional cover before booking. That way you decide not just on the cheapest price, but with a clear sense of the services you will actually receive.
What to do if the company does not respond
Inform the moving company of the damage in writing and ask for a reply within a reasonable period, for example 14 days. Stay factual: name the damage and the solution you want, and enclose your evidence. A specific claim is more helpful than a general remark that something got broken.
If the company refuses to settle, examine its reasons carefully. With high amounts, unclear responsibility or a disputed insurance policy, consumer advice or legal advice can make sense. Do not sign any final declaration while you cannot yet assess the extent of the damage.
A well-prepared move does not begin with the loading. If services, responsibilities and insurance cover are settled in advance, there is a manageable path even when damage occurs: document it, report it in time and ask for a solution you can follow. That way you arrive in your new home feeling good about it.